When do I have to send a 1099-NEC?
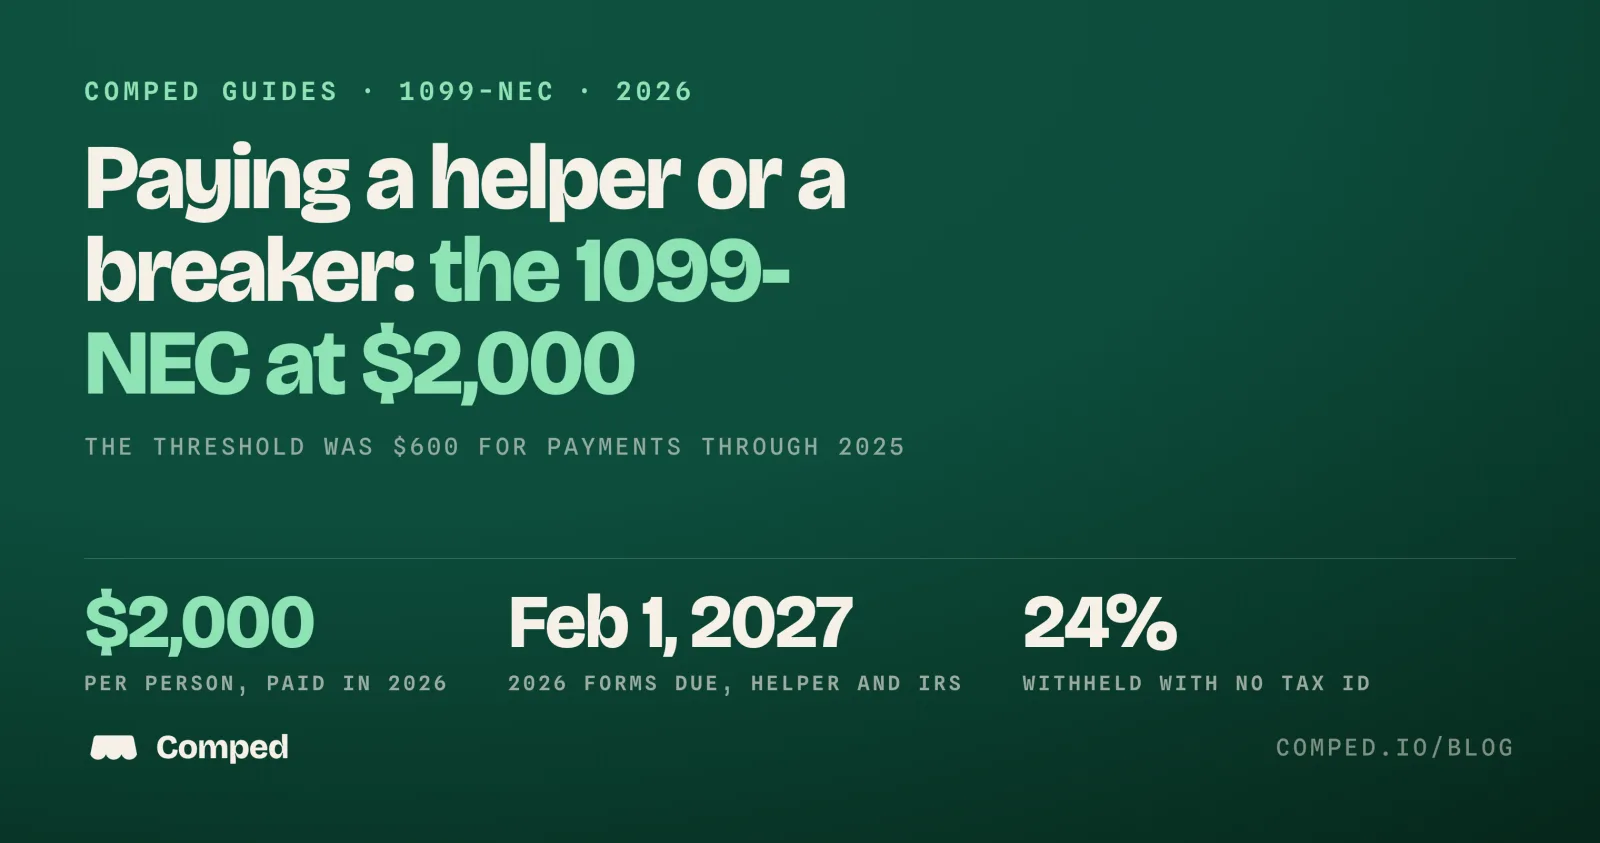
When you pay one person at least $2,000 in the year for services to your business, and that person is not your employee. The IRS instructions for Form 1099-NEC list four conditions. All four must be met.
- You made the payment to someone who is not your employee.
- You made the payment for services in the course of your trade or business.
- You made the payment to an individual, partnership, estate or, in some cases, a corporation.
- You made payments to the payee of at least $2,000 during the year.
WHAT CHANGED
The threshold was $600 for payments through 2025. The IRS instructions say it increased to $2,000 for tax years beginning after 2025, and may be adjusted for inflation beginning in 2027. Forms for 2026 payments are the first to use the new figure.
The rule applies to a trade or business, which a dealer filing Schedule C is. Hobby or business covers that line, and the master tax guide covers the dealer's return.
Which payments count toward the $2,000?
Payments for services count. Payments for cards do not. The IRS instructions say payments for merchandise are not reported on Form 1099-NEC. Buying a collection from a walk-up seller for $5,000 is a purchase of merchandise, so no 1099-NEC is filed for it.
| Payment | 1099-NEC? | Why, per the IRS instructions |
|---|---|---|
| $2,000 or more in the year to a helper who works your table | Yes | Services by a non-employee |
| Under $2,000 in the year to a helper | No | Below the threshold |
| Cards bought from a seller, any amount | No | Payments for merchandise are not reported |
| Services paid by credit card or through a payment app | No | Reported on Form 1099-K by the payment company |
| Services billed by a corporation | Generally no | Payments to corporations are generally not reported |
| Wages to an employee | No | Reported on Form W-2 |
Cash, checks and bank transfers to a helper all count. Card and app payments are different. The instructions say payments by credit card, payment card or third party network are reported on Form 1099-K by the payment settlement entity. Which payment apps send a 1099-K covers that form.
The test is the year's total to one person. Once the total reaches $2,000, the form reports all of it, not the part above $2,000. A payment under $2,000 is still a business expense for you and still income for the helper. The threshold decides the paperwork only.
Who does a card vendor actually pay, and which get a form?
Most of a vendor's payments are for cards or to companies, and neither draws a 1099-NEC. The people to watch are individuals paid for work. The IRS column below is from the instructions. The last column is our reading for a card table, not IRS text.
| Who you paid | What the IRS rule turns on | Our reading |
|---|---|---|
| Friend who works your table for a day rate | Services, non-employee, year's total | 1099-NEC at $2,000 or more in the year, if paid by cash, check or transfer |
| Person who lists, photographs or ships for you | Same | Same |
| Breaker or streamer paid to sell your product | Services, non-employee | 1099-NEC at $2,000 or more, unless paid through a platform or card |
| Collector you bought cards from | Merchandise is not reported | No form. Keep the purchase receipt |
| Grading company | Payments to corporations are generally not reported; card payments go on a 1099-K | No form in the usual case |
| Show promoter, for table fees | Rent is a Form 1099-MISC item at $2,000 or more, not a 1099-NEC item | No 1099-NEC. If the promoter is not a corporation and you paid by cash or check, ask a CPA about Form 1099-MISC |
| Accountant or bookkeeper who is not incorporated | Professional service fees are listed as an example | 1099-NEC at $2,000 or more |
What does this look like for a booth helper?
Add up everything you paid each helper in the calendar year. The test is per person, not per show.
TWO HELPERS, WORKED
Say a vendor pays helpers $150 a show day in 2026, by cash and check. Both are independent contractors. Hypothetical figures.
Helper one gets a 1099-NEC showing $2,400. Helper two gets no form. The vendor deducts all $3,900, and both helpers owe tax on what they earned.
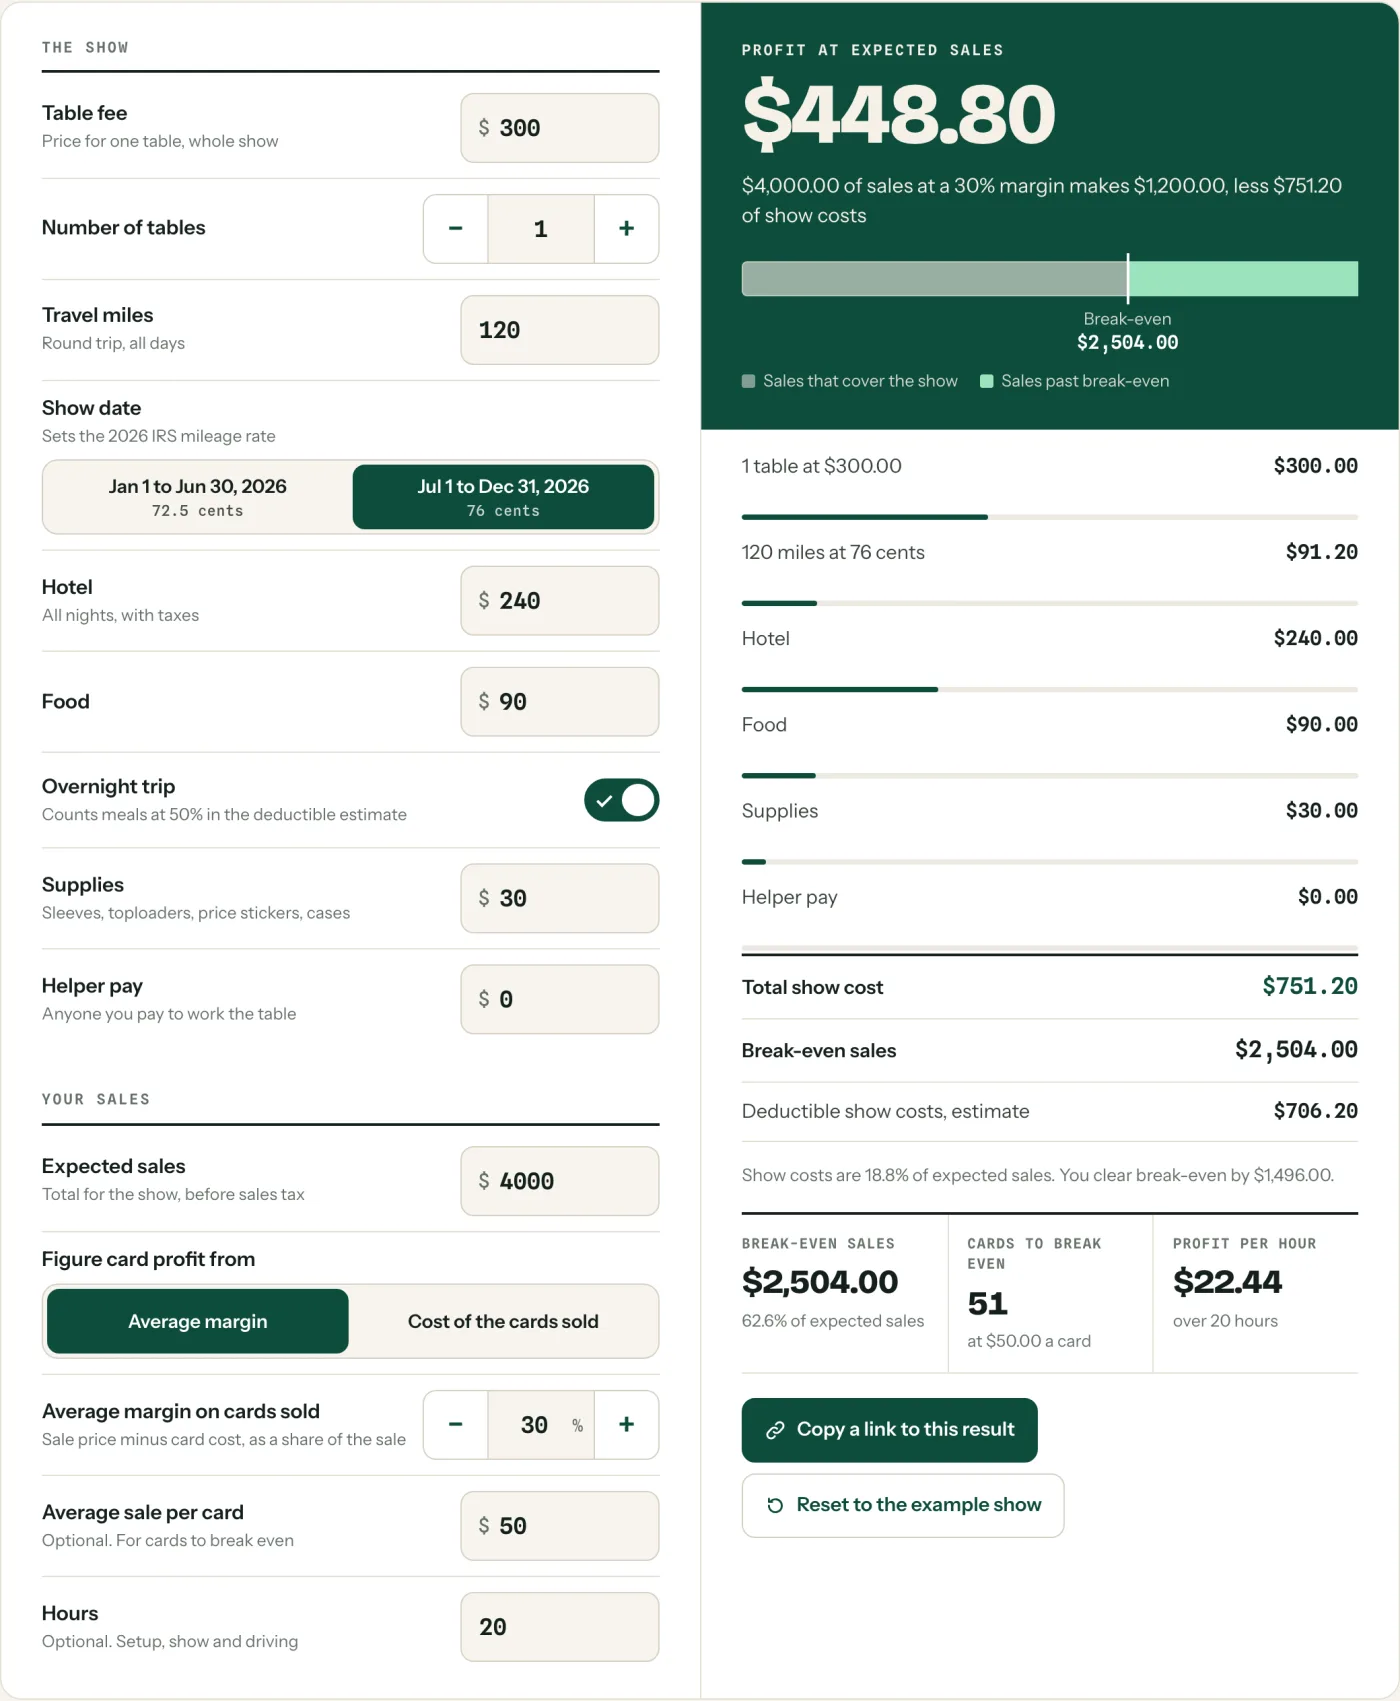
Cash pay needs a record made that day: the date, the amount, the show and the helper's name. A signed line in a notebook works. The card show cash log has a Cash out column and a note field that can hold it. The card show profit calculator shows what a helper's day rate does to a show's break-even.
Do I send a 1099-NEC to a breaker?
If you pay a breaker for a service to your business, the same four conditions apply. Paying someone to open your product on their stream or to run your show is a payment for services. At $2,000 or more in the year to a non-employee, a 1099-NEC is due.
Buying a spot in someone else's break is different. You are a customer buying cards, and the IRS instructions exclude payments for merchandise. That reading is ours. No IRS page addresses breaks, so ask a CPA about an arrangement that mixes a service fee with product.
How you paid matters here too. A breaker paid through a marketplace or by card falls under the 1099-K rule in the table above, and the payment company does the reporting.
When do I collect a W-9?
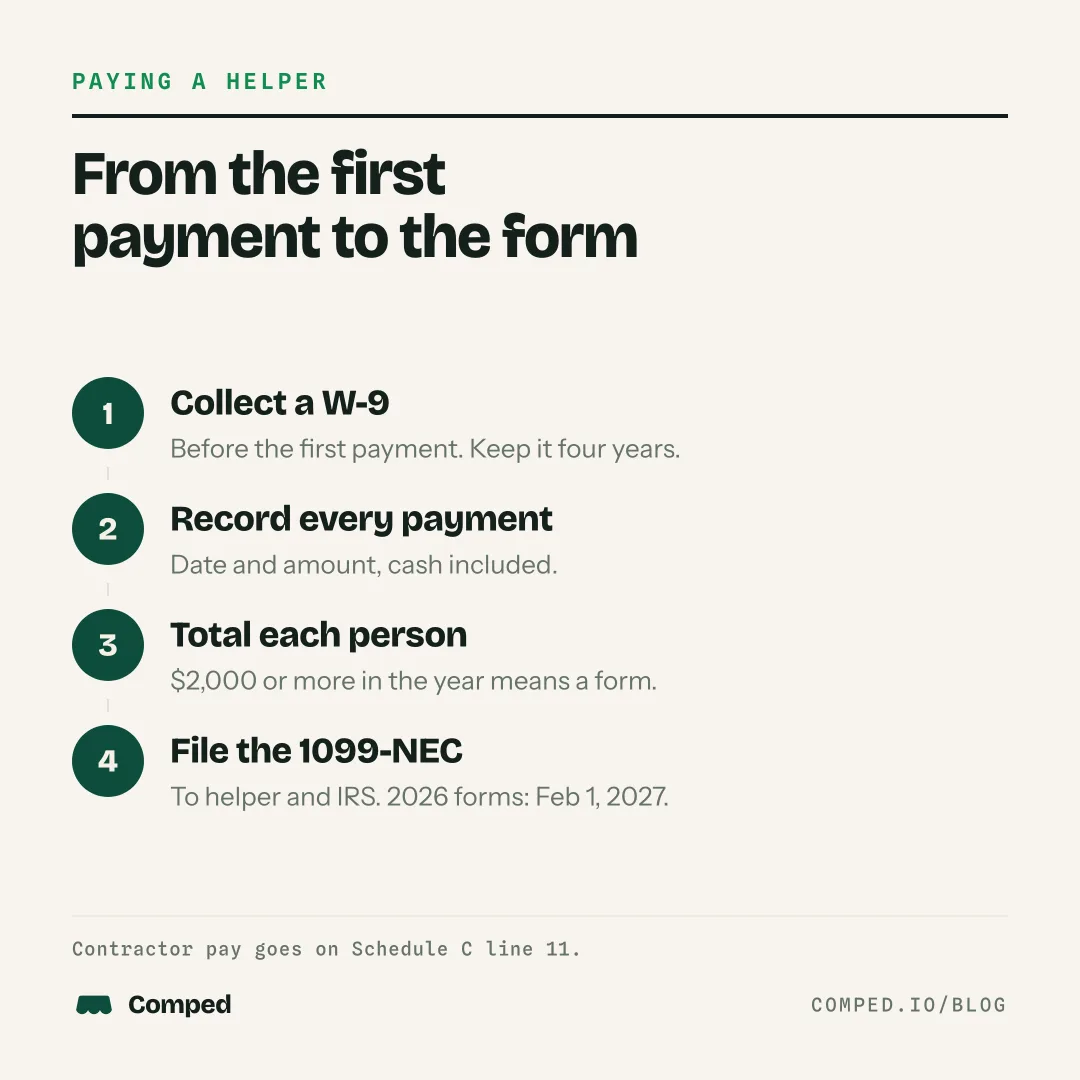
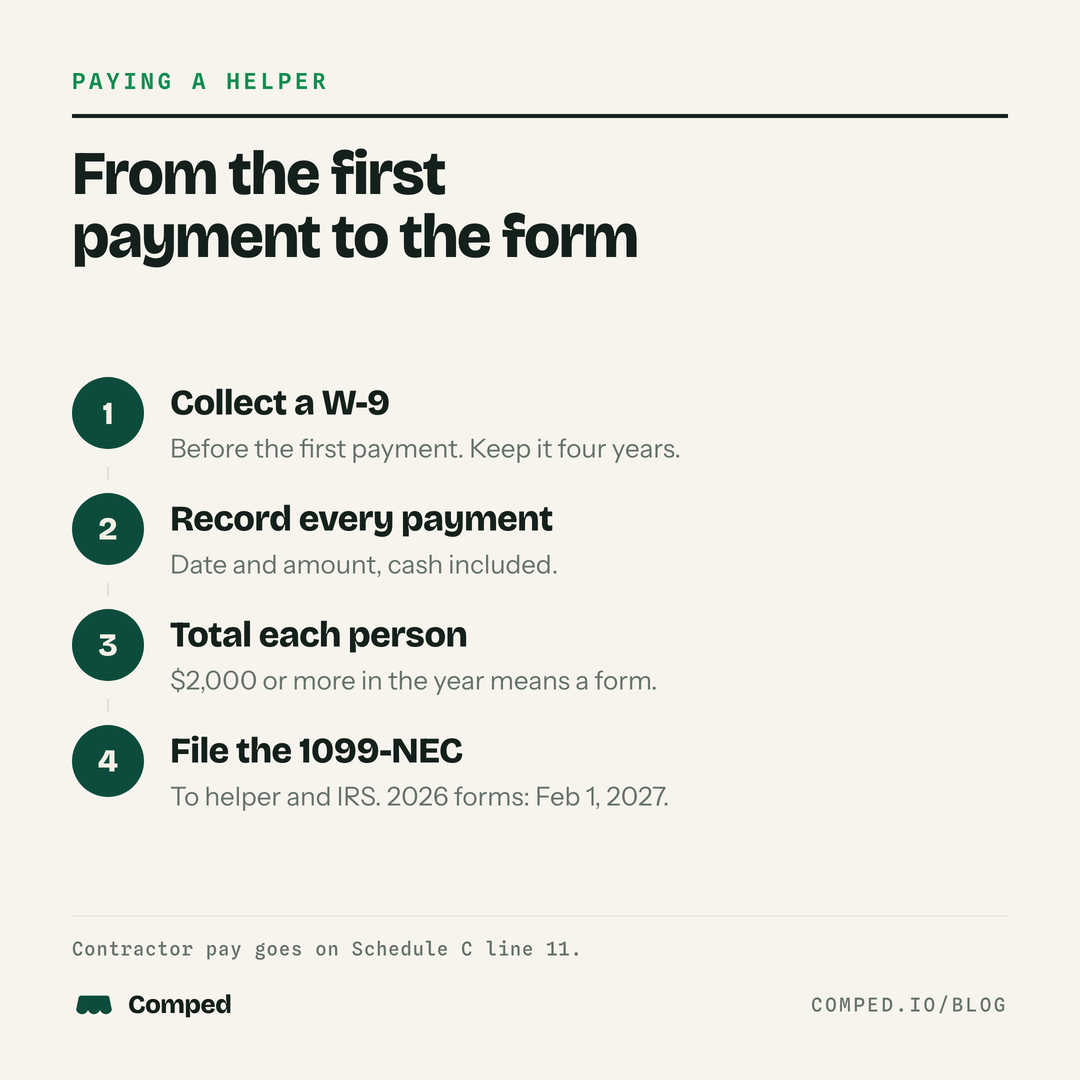
Before the first payment. The IRS page on forms for independent contractors says the first step is to have the contractor complete Form W-9. It gives you the name and taxpayer identification number that go on the 1099-NEC.
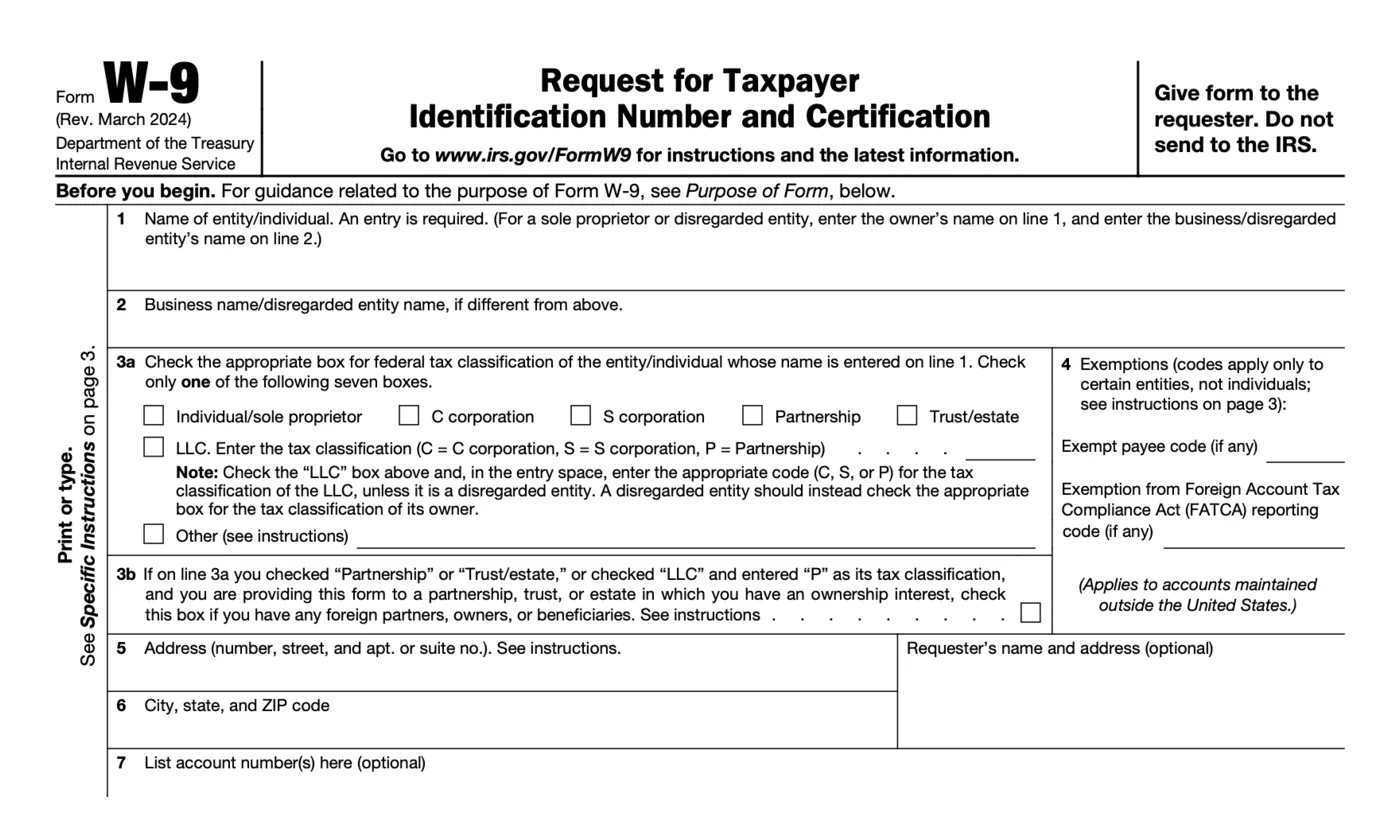
Line 3a tells you whether the payee is an individual, a partnership or a corporation, which decides the third condition. The IRS says to keep the W-9 in your files for four years. You do not send it to the IRS.
If a helper will not give a taxpayer identification number, the IRS says you must withhold 24% from reportable payments. That is backup withholding.
Your own tax ID goes on the 1099-NEC too. A sole proprietor can get an EIN free from the IRS and use it in place of a Social Security number. Do card show vendors need an LLC? covers the EIN.
What goes in each box of Form 1099-NEC?
For a booth helper, one money box matters: Box 1a, nonemployee compensation. The form was revised in December 2026, and the old Box 1 is now Box 1a. Boxes 1b, 1c and 1d are new and cover cash tips, a tipped occupation code and overtime.
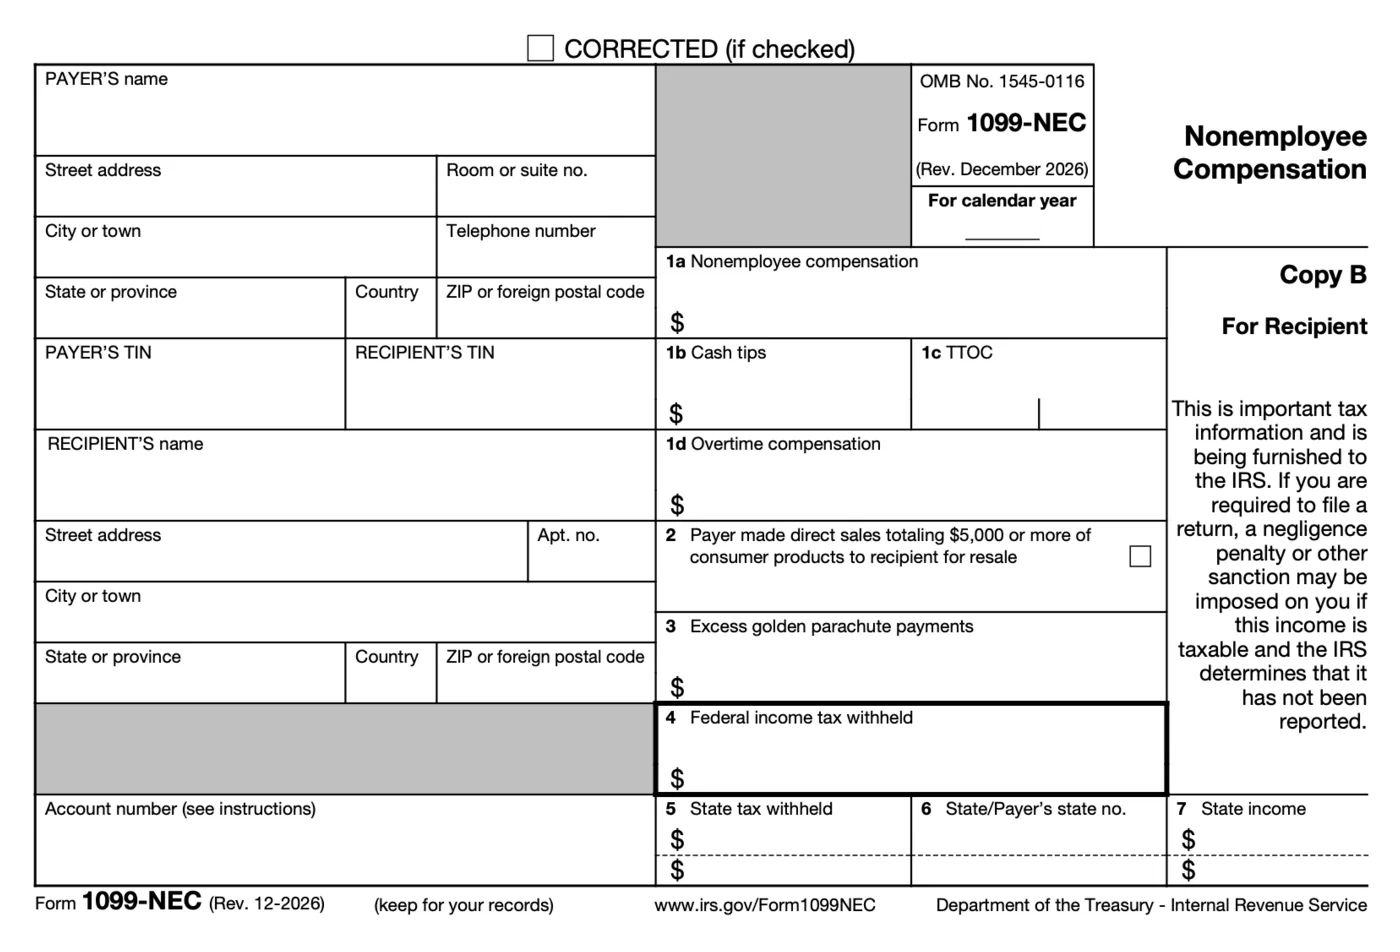
| Field | What a vendor enters |
|---|---|
| Payer's name, address and TIN | Your name or business name and your EIN or Social Security number |
| Recipient's name, address and TIN | From the helper's W-9 |
| Box 1a | The year's total paid for services, $2,000 or more |
| Box 4 | Any backup withholding you took at 24% |
| Boxes 5 to 7 | State items, where your state uses them |
The instructions allow one privacy step. On the helper's copy you may show only part of the helper's tax ID. On the copy filed with the IRS you may not.
When is the form due, how do I file, and where does the pay go on my return?
The 1099-NEC is due to the helper and to the IRS by 31 January. The IRS instructions give the same date for both. In 2027, 31 January is a Sunday. Publication 1099 says a due date that falls on a Saturday, Sunday or legal holiday moves to the next business day. Forms for 2026 payments are due Monday, 1 February 2027.
| When | What to do |
|---|---|
| Before the first payment | Collect a signed Form W-9 |
| Each payment | Record the date, amount and method |
| 31 December 2026 | Total each person's 2026 pay and compare with $2,000 |
| Early January 2027 | Set up your filing method; the IRS portal needs a code you apply for |
| Monday, 1 February 2027 | Form 1099-NEC due to each helper and to the IRS |
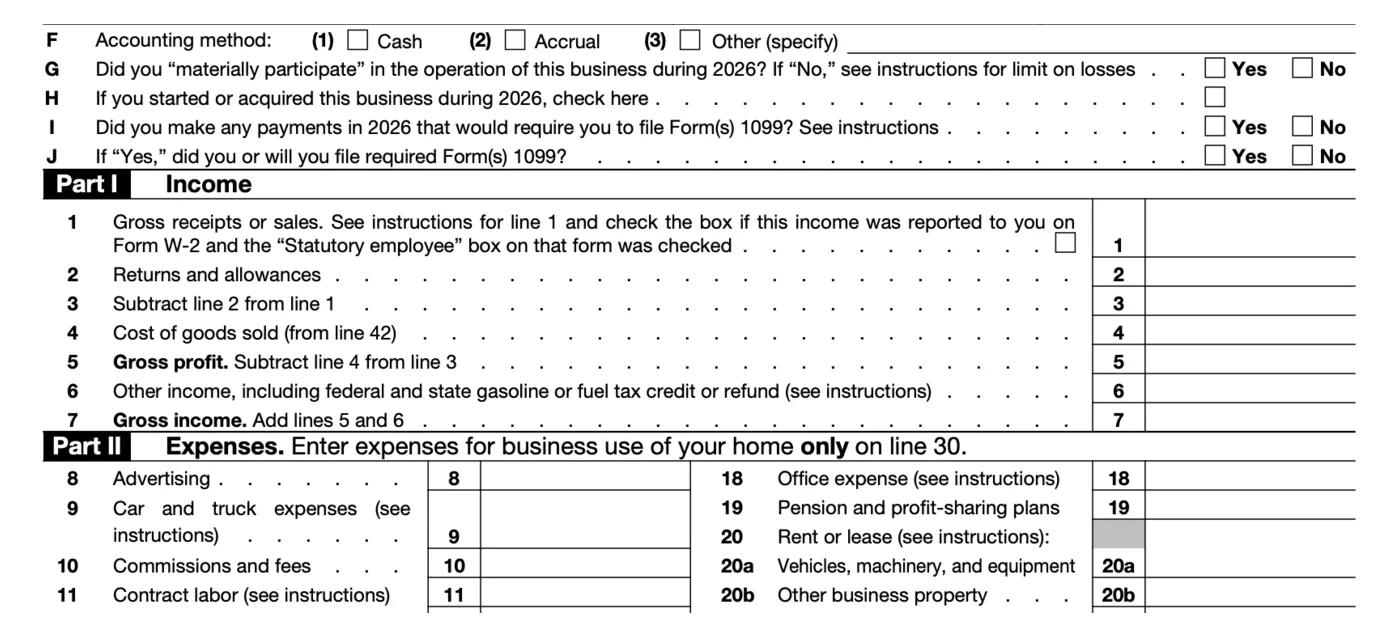
| Your 2026 return | Answer lines I and J on Schedule C and enter the pay on line 11 |
The IRS runs a free filing site, the IRIS Taxpayer Portal. It handles Form 1099-NEC, lets you download the recipient copies, and takes corrections. You need an IRIS Transmitter Control Code to use it, so apply before January.
The IRS says filers of 10 or more information returns in a year must file electronically. A vendor with one or two helpers may file on paper under the rules in Publication 1099.
On the 2026 Schedule C, contractor pay goes on line 11, contract labor. Employee wages go on line 26. Line I asks whether you made any payments in 2026 that require a Form 1099, and line J asks whether you filed them.
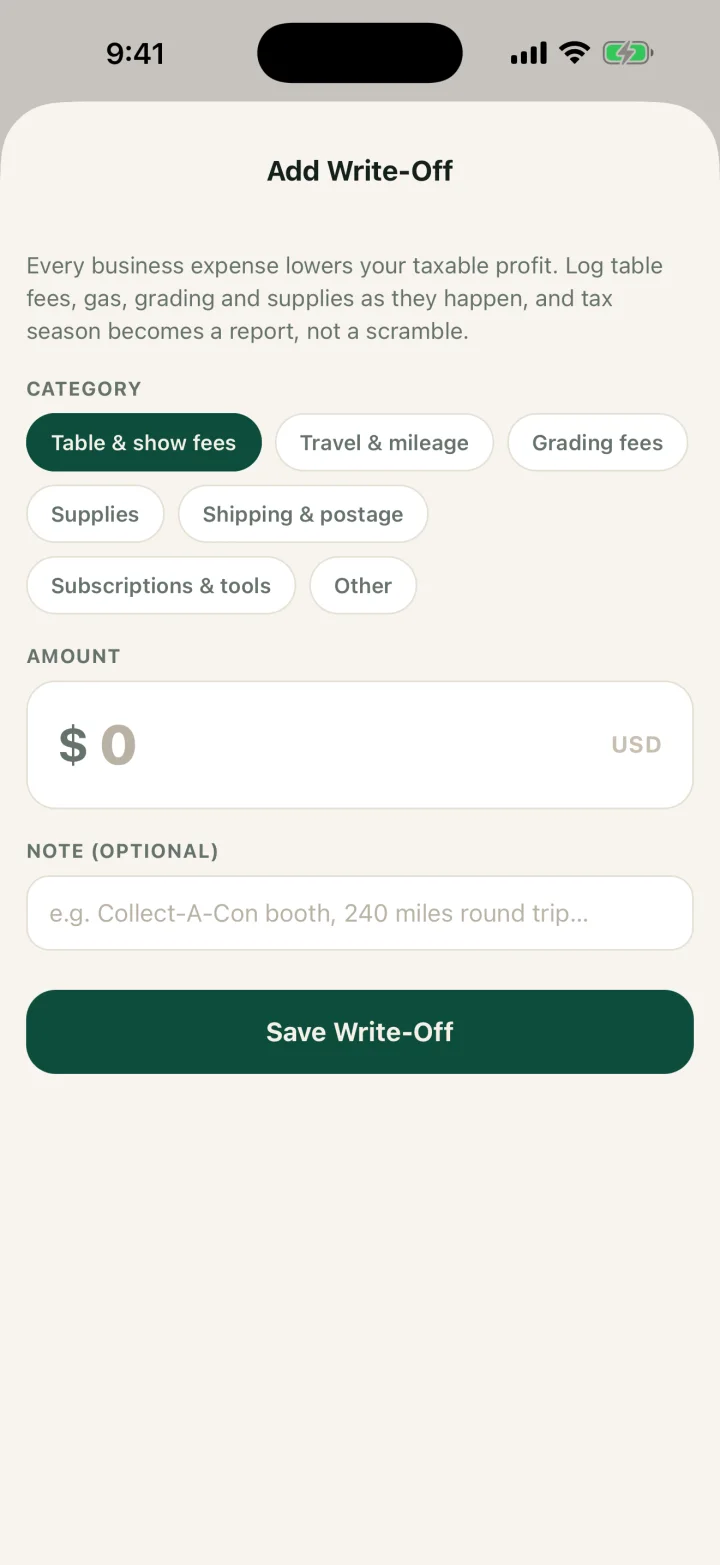
Comped has a write-off form with an amount and a note, so helper pay recorded as it happens is already totaled at year end. The master guide to write-offs lists the other show costs a dealer deducts.
What if I file late, or missed a form for last year?
File it now. The penalty grows with time, and the lowest tier is for forms no more than 30 days late. The IRS information return penalties page lists these amounts for returns due in 2027.
| How late | Penalty per return or statement, due in 2027 |
|---|---|
| Up to 30 days late | $60 |
| 31 days late through 1 August | $130 |
| After 1 August, or not filed | $340 |
| Intentional disregard | $690 |
The amounts are per return or statement. The form filed with the IRS and the copy owed to the helper are each covered.
Payments made in 2025 used the old $600 threshold, and those forms were due in early 2026. If you paid a helper $600 or more in 2025 and filed nothing, the form is late, not excused by the new figure. The same IRS page lists $340 per return or statement for 2026 due dates once 1 August has passed.
If a form you filed was wrong, file a corrected one. The 1099-NEC has a Corrected box at the top, and IRIS accepts corrections.
Is my helper a contractor or an employee?
The IRS decides by the degree of control and independence, not by what you call the helper. Its page on independent contractor or employee groups the facts into three categories.
| Category | The question the IRS asks |
|---|---|
| Behavioral | Does the company control or have the right to control what the worker does and how the worker does the job? |
| Financial | Are the business aspects of the job controlled by the payer: how the worker is paid, whether expenses are reimbursed, who provides tools? |
| Type of relationship | Are there written contracts or employee-type benefits, will the relationship continue, and is the work a key aspect of the business? |
The IRS says there is no magic or set number of factors that makes a worker an employee or a contractor. Document the factors you used.
The answer changes your duties. For an employee, the IRS says you must withhold income, Social Security and Medicare taxes, pay the employer share and pay unemployment tax. Wages go on Form W-2. For a contractor, you generally do not withhold or pay taxes on the payments.
Getting it wrong has a cost. Treat an employee as a contractor with no reasonable basis, the IRS says, and you may be held liable for that worker's employment taxes. Either you or the worker can file Form SS-8 and ask the IRS to decide. The IRS says a determination can take at least six months.
What if I am the helper and I got a 1099-NEC?
Report the amount as self-employment income. The Schedule C instructions say line 1 must include amounts properly shown on your Forms 1099-NEC. Self-employment tax of 15.3% applies once net earnings reach $400.
Pay under $2,000 produces no form and is taxable all the same. If you also sell cards, quarterly estimated taxes for card sellers covers paying during the year.
How this looks in the Comped app
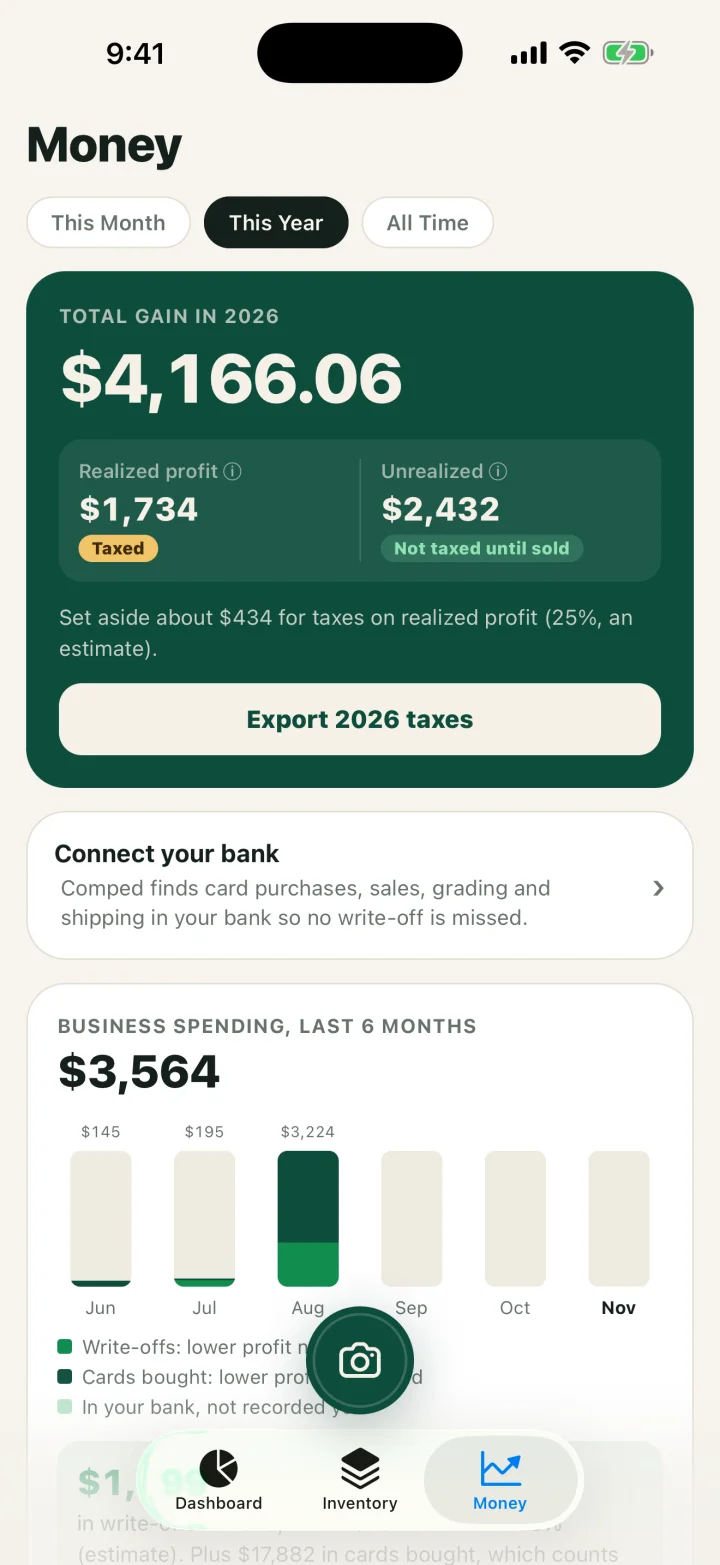
The first screen is the write-off form. A helper's day pay goes in as an amount with a note naming the person and the show. The second is the Money tab, where business spending is totaled by month and Export taxes produces a CSV listing every write-off for the year.
Related guides
- The Card Vendor's Master Guide to Taxes: the dealer's Schedule C, including labor.
- The Card Vendor's Master Guide to Write-Offs: helper pay next to table fees, mileage and supplies.
- Do card show vendors need an LLC?: the EIN, and what an entity changes.
- Which table payments send a 1099-K: the form for payments made through apps and cards.
FAQ
What is the 1099-NEC threshold for 2026?
$2,000. The IRS instructions say the threshold increased from $600 to $2,000 for tax years beginning after 2025. It may be adjusted for inflation beginning in 2027. It applies to the total you pay one person in the year.
I paid my helper in cash. Does that count?
Yes. Cash payments for services count toward the $2,000 the same as checks. Record each payment with the date and amount, and collect a Form W-9 before the first one.
Do I send a 1099-NEC when I buy cards from someone?
No. The IRS instructions say payments for merchandise are not reported on Form 1099-NEC. The form covers services. Keep a receipt for the purchase, because it is your cost for the cards.
Do I send a 1099 to someone I paid on Venmo or PayPal?
The IRS instructions say payments made by payment card or through a third party network are not reported on Form 1099-NEC. The payment company reports them on Form 1099-K when its own threshold is met. Whether a personal, friends and family transfer counts is not addressed by the IRS page, so ask a CPA.
My helper earned less than $2,000. Does the helper still owe tax?
Yes. The threshold decides whether you file a form, not whether the income is taxable. You still deduct the pay, and the helper still reports it.
Can I just call my helper a contractor?
No. The IRS looks at behavioral control, financial control and the type of relationship, not at the label. A business that misclassifies an employee with no reasonable basis may be liable for employment taxes.
What if my helper will not fill out a W-9?
The IRS says you must withhold 24% from reportable payments to a person who has not provided a taxpayer identification number. This is backup withholding. Ask for the W-9 before any work starts.
What is the penalty for filing a 1099-NEC late?
For returns due in 2027 the IRS lists $60 per return or statement if up to 30 days late, $130 through August 1, and $340 after that or if never filed. Intentional disregard is $690. Filing as soon as you notice keeps the amount in the lowest tier still open.
SOURCES
- Instructions for Forms 1099-MISC and 1099-NEC (revised December 2026), IRS, checked November 2026.
- Form 1099-NEC (Rev. December 2026), IRS, checked November 2026.
- About Form 1099-NEC, IRS, checked November 2026.
- Publication 1099 (2026), General Instructions for Certain Information Returns, IRS, checked November 2026.
- Information return penalties, IRS, checked November 2026.
- E-file information returns with IRIS, IRS, checked November 2026.
- Forms and associated taxes for independent contractors, IRS, checked November 2026.
- Reporting payments to independent contractors, IRS, checked November 2026.
- Independent contractor (self-employed) or employee?, IRS, checked November 2026.
- Schedule C (Form 1040), 2026, IRS, and its 2025 instructions, checked November 2026.
This is general information for card sellers, not tax or legal advice for your situation. Rules change and states differ; a CPA who knows your numbers wins every time.