Placed in service by December 31
The date that counts is when the gear is ready to use, not when you pay for it. Publication 946 says you place property in service when it is ready and available for a specific use. The master guide to write-offs covers the rest of a card business's deductions.
A scanner ordered on December 20 and delivered on January 4 is 2027 property. Cases that arrive on December 29 and are set up for the next show count for 2026. Keep the delivery confirmation with the invoice.
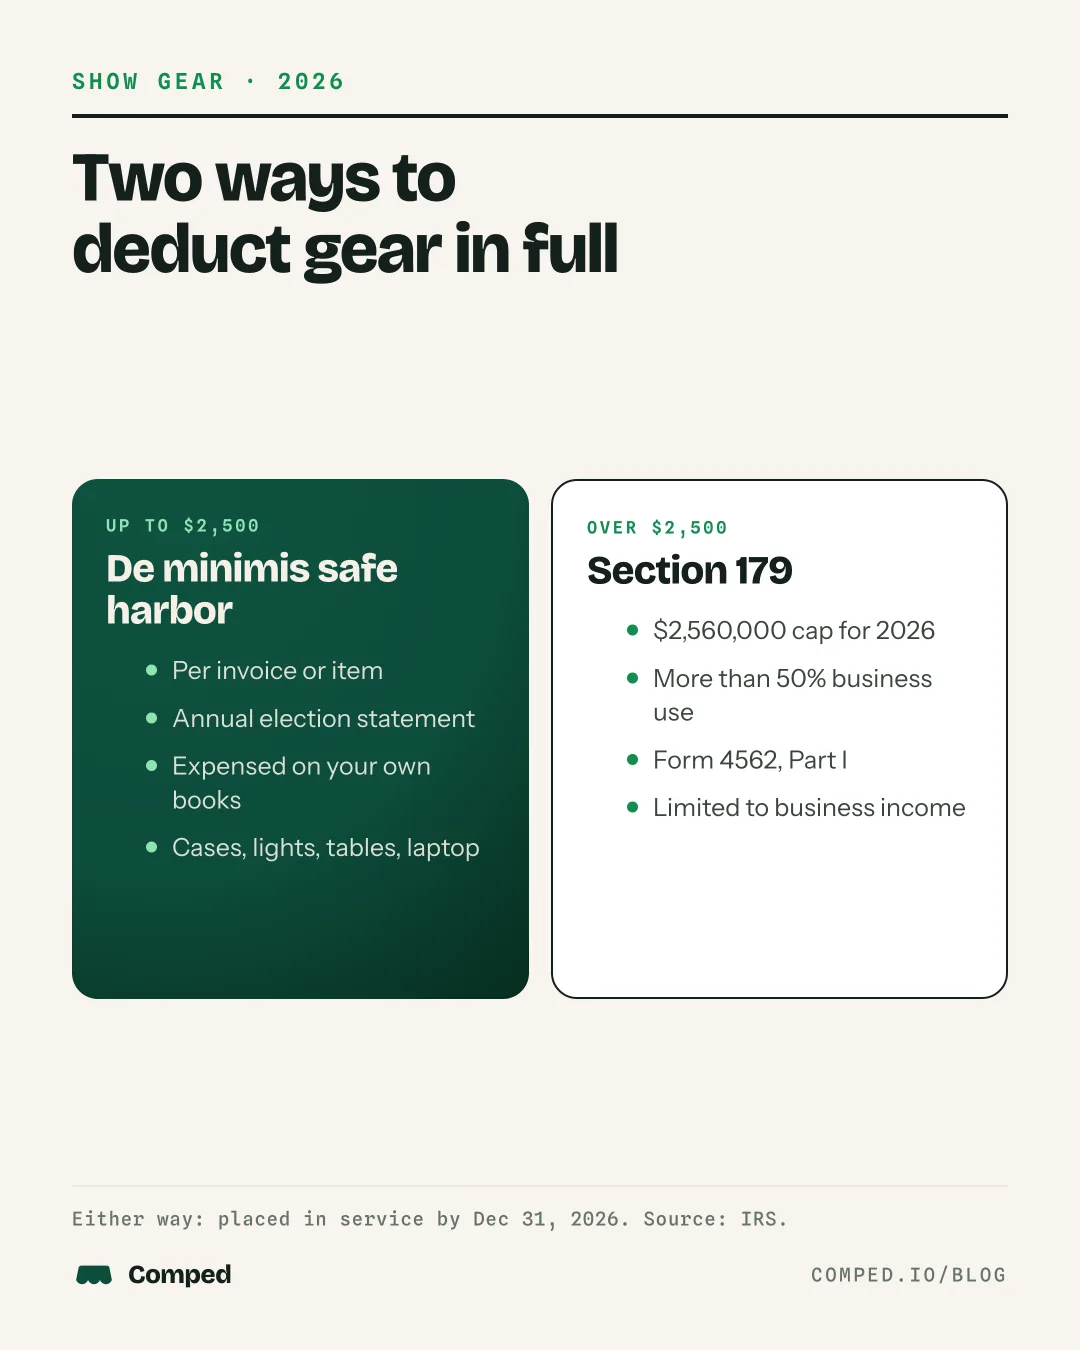
The $2,500 de minimis safe harbor
The de minimis safe harbor lets you deduct gear costing up to $2,500 per invoice or item as an ordinary expense. The IRS page on the tangible property regulations sets that limit for businesses without an applicable financial statement. It has been $2,500 since tax years beginning January 1, 2016.
It is an election you make every year. You attach a statement titled "Section 1.263(a)-1(f) de minimis safe harbor election" to your timely filed original return, including extensions. The statement gives your name, address and taxpayer identification number and says you are making the election.
There is one condition people miss. You must expense these amounts on your own books under a policy in place at the start of the tax year. The policy does not have to be written, but it has to be how you already treat small purchases.
THE RULE PEOPLE GET WRONG
The $2,500 is per invoice or item, as substantiated by the invoice. Keep invoices that list each item and its price. A single receipt with one total is harder to split later.
Section 179 for 2026
Section 179 lets you deduct the full cost of larger equipment in the year you place it in service. For tax years beginning in 2026, Rev. Proc. 2025-32, section 4.24, caps it at $2,560,000. The cap is reduced once total Section 179 property placed in service in 2026 passes $4,090,000.
No card vendor comes near those limits. The limit that matters is business income. Publication 946 says the deduction cannot exceed taxable income from the active conduct of a business. Any cost over that carries to the next year.
The gear must be used more than 50% for business in the year you place it in service. You make the election on Form 4562, Part I, and the deduction lands on Schedule C line 13. Property bought from a family member or other related person does not qualify.
100% bonus depreciation
Bonus depreciation also gives a full first-year deduction, and it is back at 100%. Publication 946 says the July 2025 law reinstated the 100% special depreciation allowance for qualified property acquired after January 19, 2025. The property also has to be placed in service after that date.
It applies unless you elect out. Publication 946 lets you elect, for any class of property, not to take the special allowance, on a timely filed return. For a vendor whose business income covers the cost, Section 179 and bonus reach the same answer: the full cost off 2026 profit.
Card show gear, item by item
Gear used to sell cards is an ordinary and necessary business cost under Publication 334. The route depends on the price of each item. The amounts below are examples, not quotes.
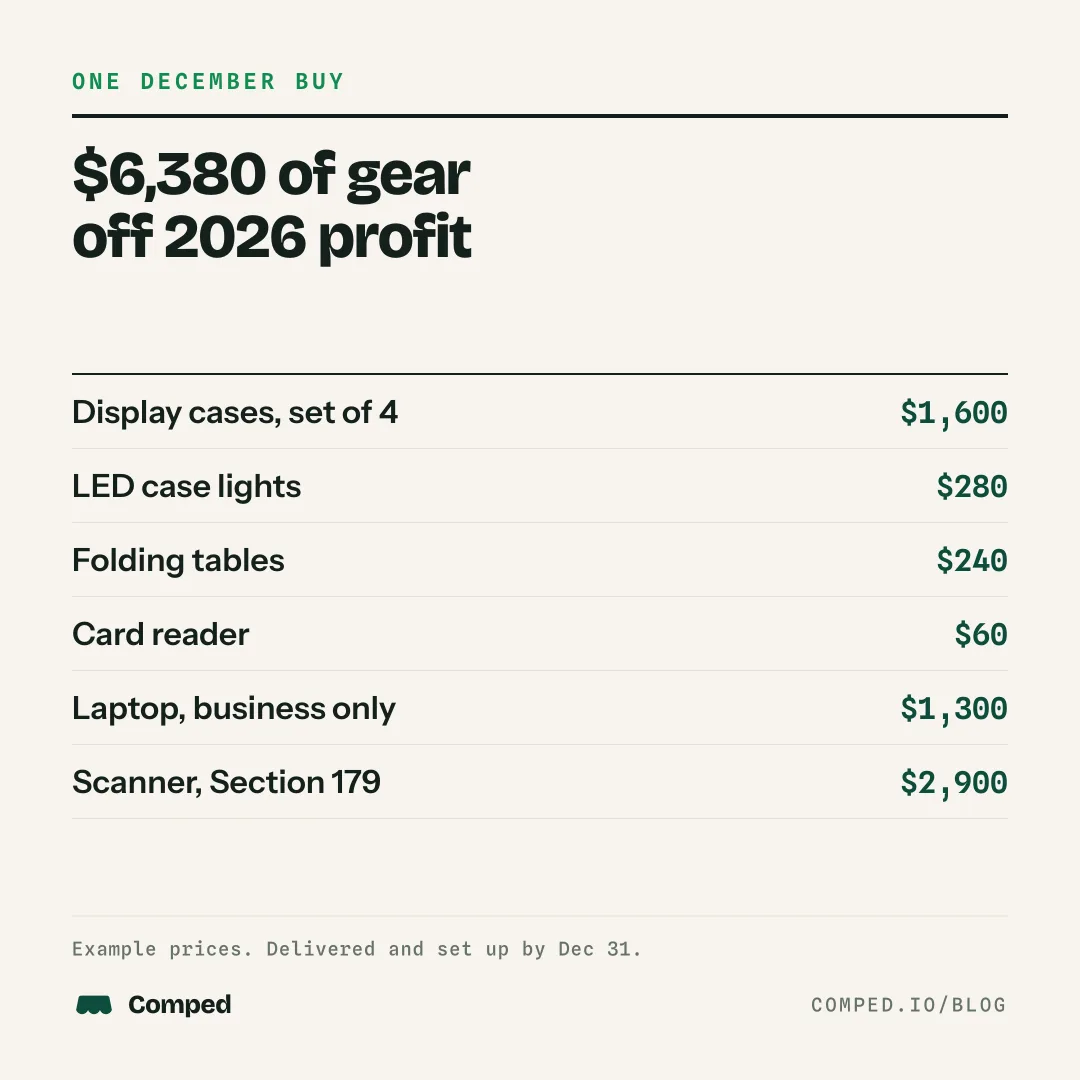
| Item | Example cost | Route for 2026 |
|---|---|---|
| Glass display cases, set of 4 | $1,600 | De minimis, $2,500 or less |
| LED case lights | $280 | De minimis |
| Folding tables and table covers | $240 | De minimis |
| Card reader for payments | $60 | De minimis |
| Laptop, business use only | $1,300 | De minimis |
| High-speed card scanner | $2,900 | Section 179 or bonus, Form 4562 |
A laptop or phone you also use personally is deducted only for its business share. Under Section 179 it also has to pass the more than 50% business use test.
Gear is not inventory. Cases and scanners are equipment, while the cards in them are stock. The cards follow the rules in our post on counting card inventory at year end.
The worked example
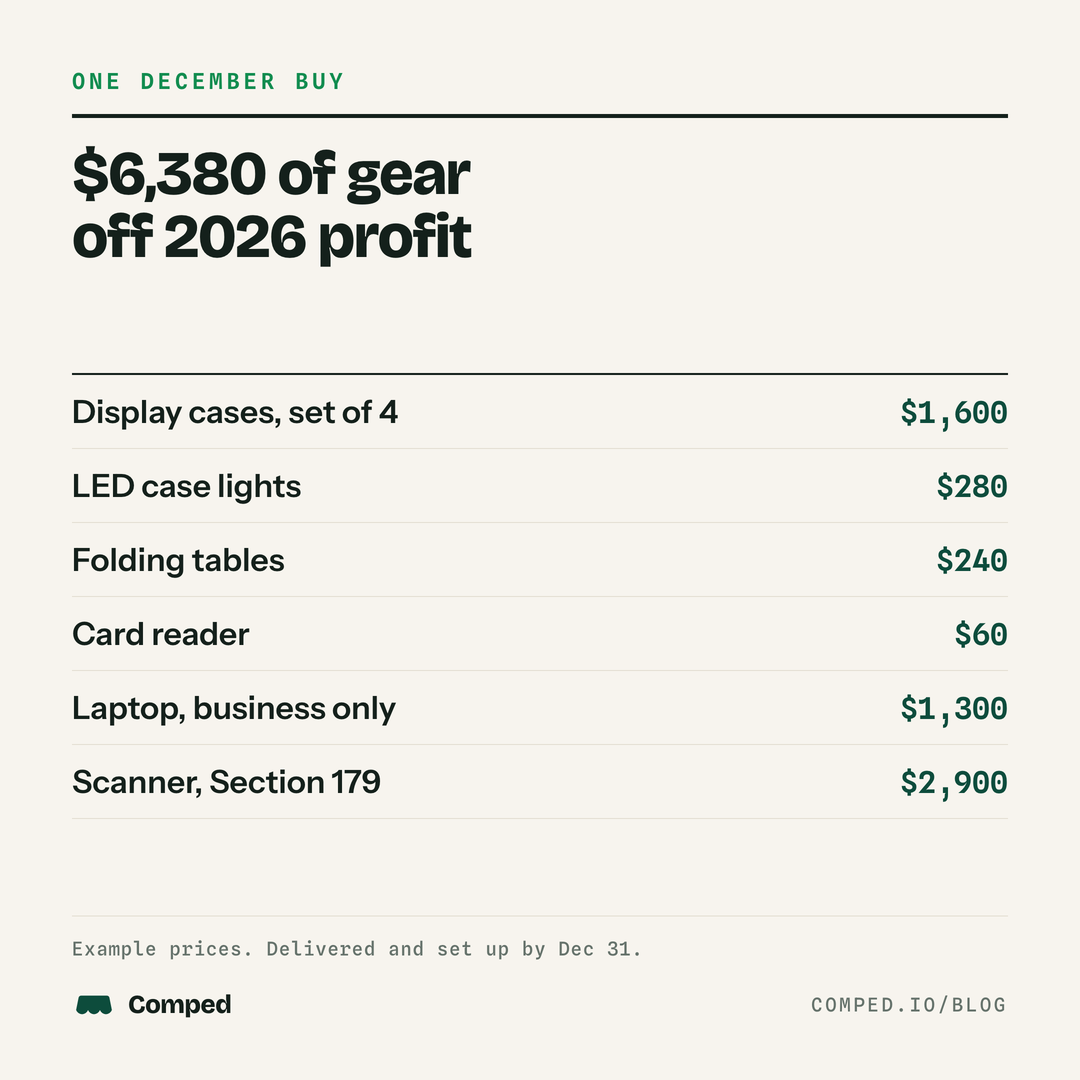
Say a vendor buys the gear in the table in December 2026. It is all delivered and set up by December 31, with an itemized invoice for each purchase.
A DECEMBER BUY, WORKED
Everything placed in service by December 31, 2026.
Each item is under $2,500 except the scanner, so the scanner goes through Form 4562. If the scanner had arrived on January 4, its $2,900 would belong to 2027.
What the deduction is worth
A deduction saves the tax on the amount, not the amount itself. For a vendor in the 22% bracket who also pays 15.3% self-employment tax, a $1,000 purchase saves roughly $300 to $350. Buying gear you would not otherwise buy still costs you money.
Buy what you need for next season, and have it in hand by December 31 if you want it on the 2026 return. The guide to taxes on selling sports cards shows how profit becomes tax owed.
Run a sale through the card sale tax calculator to see the tax to set aside.
Related guides
- The Card Vendor's Master Guide to Write-Offs: every deduction a card business has, with the record that proves each one.
- How to count card inventory at year end: the December 31 count and Schedule C lines 35 to 42.
- Do you have to pay taxes on selling sports cards?: every step from sale price to tax owed.
- Do card show vendors need an LLC?: what an LLC changes and what it does not.
FAQ
Are display cases tax deductible?
Yes, for a vendor who uses them to sell cards. A case set costing $2,500 or less per invoice or item can be deducted under the de minimis safe harbor. A more expensive set can be deducted in full under Section 179 or bonus depreciation if placed in service by December 31, 2026.
What is the Section 179 limit for 2026?
$2,560,000 for tax years beginning in 2026, reduced once total Section 179 property placed in service passes $4,090,000. The figures come from Rev. Proc. 2025-32. The deduction also cannot exceed your business taxable income for the year.
What is the de minimis safe harbor $2,500 rule?
Businesses without an applicable financial statement can deduct tangible property costing up to $2,500 per invoice or item instead of depreciating it. You elect it each year with a statement attached to your timely filed return, including extensions. You must also expense such items on your own books under a policy in place at the start of the year.
If I pay in December but the scanner ships in January, does it count for 2026?
No. The deduction follows the date the property is placed in service, which is when it is ready and available for use. A scanner that arrives in January 2027 is deducted on the 2027 return.
Is buying equipment to lower my taxes worth it?
Only if you need the equipment. A deduction saves the tax on the cost, not the cost itself. For a vendor in the 22% bracket paying self-employment tax, that is roughly $300 to $350 per $1,000. The rest is money spent.
SOURCES
- Rev. Proc. 2025-32, section 4.24, IRS, checked November 4, 2026.
- Publication 946 (2025), How To Depreciate Property, IRS, checked November 4, 2026.
- Tangible property final regulations, IRS, checked November 4, 2026.
- Publication 334 (2025), Tax Guide for Small Business, IRS, checked November 4, 2026.
- Schedule C (Form 1040) 2026, IRS, checked November 4, 2026.
- Self-employment tax, IRS, checked November 4, 2026.
This is general information for card sellers, not tax or legal advice for your situation. Rules change and states differ; a CPA who knows your numbers wins every time.